What condo insurance in Dallas, TX actually covers
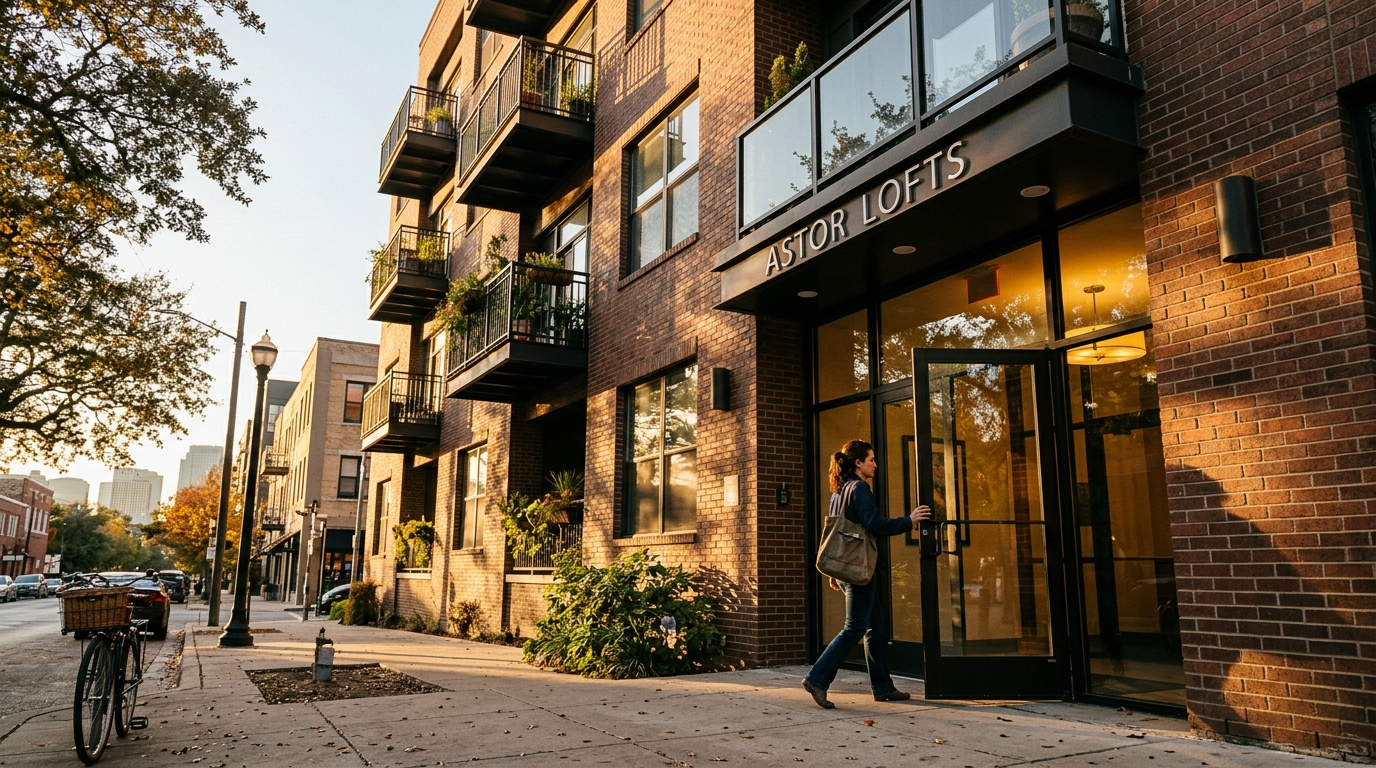
Condo insurance in Dallas, TX works differently from a standard homeowners policy, and that difference catches a lot of buyers off guard at claim time. When you purchase a condo, you own the interior of your unit. The homeowners association (HOA) owns the building shell, the roof, and the common areas. That split ownership means you need a specific type of policy, called an HO-6, to cover the gap between what the HOA's master policy protects and what you actually stand to lose.
Dallas has a growing condo market. From Uptown and the Design District to East Dallas and the Frisco corridor to the north, more Texans are choosing condo living every year. Understanding how an HO-6 policy works here, in this state, in this market, will help you make a sound coverage decision rather than simply buying whatever seems cheapest at the time.
How the HOA master policy affects your coverage
Before you can determine what you need on your own policy, you have to understand what your HOA already covers. Most Dallas condo associations carry one of two types of master policies:
- Bare walls-in : covers the building structure, common areas, and original fixtures only. Everything inside your unit, including flooring, cabinets, appliances, and any upgrades you made, is your responsibility.
- All-in (or all-inclusive) : covers original fixtures and built-ins inside your unit, but still leaves your personal belongings and improvements unprotected.
Request a copy of your HOA's master policy declaration page before you buy your own coverage. Your agent needs to see it. If your HOA runs a bare walls-in policy and you skip personal property coverage or underinsure your unit improvements, you could be left paying out of pocket for a kitchen remodel after a water loss even if your neighbor's leak caused the damage.
What a standard HO-6 policy includes
A condo insurance policy in Texas typically bundles several coverage types under one premium. A well-structured HO-6 generally includes the following:
- Dwelling coverage (Coverage A) : pays to repair or replace interior structures and improvements, such as hardwood floors, tile, built-in shelving, or a remodeled bathroom, up to your policy limit.
- Personal property coverage (Coverage C) : covers your furniture, clothing, electronics, and other belongings if they are stolen or damaged by a covered peril. Replacement cost coverage is worth paying extra for; actual cash value pays you what the item is worth today, not what it costs to replace it.
- Loss of use (Coverage D) : if a covered loss makes your unit uninhabitable, this pays for temporary housing and additional living expenses while repairs are made.
- Personal liability (Coverage E) : protects you if a guest is injured in your unit or if you accidentally damage another unit (a common scenario with plumbing issues in stacked condos). Most policies start at $100,000 , but $300,000 to $500,000 is a more appropriate baseline given the litigation environment.
- Medical payments (Coverage F) : pays minor medical bills for guests injured on your property, regardless of fault, typically $1,000 to $5,000 .
- Loss assessment coverage : easy to overlook. If your HOA suffers a loss that exceeds its own master policy, say a major hail event damages the roof, the association can pass the shortfall to unit owners through a special assessment. Loss assessment coverage pays your share. In North Texas, where hail is a regular seasonal event, this coverage matters.
Dallas-specific risks that shape your coverage needs
Living in Dallas comes with specific weather and risk patterns that should influence how you build your condo policy. North Texas ranks among the most active hail regions in the United States, earning the area its "Hail Alley" nickname. The Dallas-Fort Worth metro sees an average of 10 or more significant hail events per year, and tornado activity is a genuine seasonal concern from March through June.
Wind and hail are standard covered perils on most HO-6 policies, but there are a few things to check. First, confirm your policy's deductible structure. Some Texas policies carry a separate wind and hail deductible , often stated as a percentage of your dwelling coverage rather than a flat dollar amount. A 1% wind/hail deductible on a $200,000 dwelling limit means you pay the first $2,000 out of pocket before coverage applies. That is a meaningful number if a storm pushes water through your sliding glass door and damages your floors.
Flooding is the other major risk. Dallas sits in a region with numerous flood-prone creek corridors, and heavy rainfall events have become more frequent and intense. Standard HO-6 policies do not cover flood. If your condo building sits near White Rock Creek, Bachman Creek, or any of the other waterways that have flooded in recent years, a separate flood insurance policy deserves serious consideration. The NFIP offers policies through licensed agents, and some private carriers offer alternatives worth comparing.
What condo insurance costs in Dallas
Rates for condo insurance in Dallas typically run between $400 and $900 per year for a moderately priced urban unit with standard limits. That translates to roughly $33 to $75 per month . Your actual premium depends on several factors:
- Your unit's value and improvements : a renovated Uptown high-rise unit with quartz counters and custom built-ins needs more dwelling coverage than a stock unit in a suburban complex.
- Personal property value : take a home inventory. Most people underestimate how much their belongings are worth until they have to replace everything at once.
- Your liability limit : higher limits cost more, but the gap between $100,000 and $300,000 in coverage is often only a few dollars per month.
- Your deductible choice : raising your deductible from $500 to $1,000 or $2,500 can reduce your premium noticeably, but make sure you can cover that amount if you need to file a claim.
- Your claims history and credit score : Texas insurers use credit-based insurance scores to price policies. Keeping your credit in good shape can translate directly to lower premiums.
- Building age and construction type : an older mid-rise in the Lakewood area may carry different risk factors than a new concrete construction high-rise in Victory Park.
Working with an independent agent who can shop multiple carriers at once is the most reliable way to find the best rate for your specific situation. Carriers price Texas condo insurance differently, and the gap between the least competitive and most competitive quote can be $200 or more per year for the same coverage level.
Common mistakes Dallas condo owners make
A few patterns come up repeatedly when something goes wrong for condo owners across the Dallas market:
- Assuming the HOA covers everything : it does not. The master policy protects the association's interest in the shared structure, not your personal property or your unit improvements.
- Skipping loss assessment coverage : hailstorms that damage a roof or parking structure can generate a special assessment. Without this coverage, that bill comes out of your pocket.
- Carrying actual cash value instead of replacement cost : a five-year-old laptop or a two-year-old sectional sofa depreciates quickly. Replacement cost coverage pays what it actually costs to buy an equivalent item today.
- Underinsuring unit improvements : if you or a previous owner upgraded the kitchen, replaced the flooring, or finished out a closet space, those improvements add to your replacement cost. If your dwelling coverage does not reflect those improvements, you may not fully recover after a loss.
- Forgetting about high-value items : standard personal property coverage often caps payouts for jewelry, collectibles, and electronics at a sub-limit well below their actual value. A scheduled personal articles endorsement or a separate jewelry rider fills that gap.
How to choose the right policy for your Dallas condo
Start by gathering a few key documents before you call an agent. You will want the HOA master policy declarations (specifically noting whether it is bare walls-in or all-in), a rough estimate of your personal property value (a home inventory spreadsheet works well), and a list of any upgrades made to the unit.
From there, consider how much liability exposure you carry. Do you work from home and have clients visit? Do you rent out your unit occasionally on a short-term basis? Those activities can change your coverage needs significantly. Some standard HO-6 policies include limited business activity coverage, while others exclude it outright.
If you short-term rent your Dallas condo through a platform like Airbnb or VRBO, discuss that specifically with your agent. A standard HO-6 policy almost certainly will not cover a claim that occurs during a rental period. You may need a short-term rental policy or endorsement in addition to your base condo coverage.
Finally, review your policy at renewal, not just when you first buy it. If the Dallas real estate market has pushed your unit's replacement value higher (and it has, substantially, over the past several years), your dwelling coverage limit may need to be updated to keep pace.
Get condo insurance quotes from an independent agent in Dallas
Princeton Insurance is an independent insurance agency serving Dallas and the broader North Texas area, including Plano, Frisco, Allen, McKinney, and beyond. Because we work with multiple carriers instead of just one, we can compare policies side by side and find the combination of coverage and price that makes sense for your unit, your HOA situation, and your budget.
If you are buying your first Dallas condo, switching from a policy that no longer fits, or just wondering whether you are paying too much, we are happy to take a look. Reach out to us at (469) 916-9595 or visit our contact page to request a quote. We will ask the right questions, review your HOA master policy, and make sure you are covered for what actually matters in this market.
Get A Quote
At Princeton Insurance, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Princeton Insurance
Recent Posts