What personal umbrella insurance in Texas actually does
Most people in the Dallas-Fort Worth area carry solid auto and homeowners policies and assume they're covered. Then a serious car accident happens, a guest is badly injured at their home, or a lawsuit arrives with a demand that dwarfs every limit they have. That gap is exactly what personal umbrella insurance in Texas is designed to close. It sits above your existing liability coverage and pays when those underlying limits run out, protecting your savings, your home equity, and your future income from judgments you never saw coming.
How umbrella coverage works on top of your existing policies
Your auto and homeowners policies are a first layer of defense. A standard Texas auto policy might carry $100,000 per-person bodily injury liability , and a typical homeowners policy might include $300,000 in personal liability . Those numbers sound large until a jury in Dallas or Collin County awards $600,000 to an injured plaintiff. Without an umbrella, you pay the difference out of pocket.
A personal umbrella policy kicks in once your underlying limit is exhausted. Most umbrella policies start at $1 million in additional coverage and can go up to $5 million or more. The premium is often surprisingly affordable, typically $150 to $350 per year for a $1 million policy, because the underlying policies absorb the first layer of risk.
Umbrella coverage typically extends across multiple policies at once, including your:
- Personal auto policy , which covers liability from accidents you cause on Texas roads
- Homeowners or renters policy , which covers liability arising from your property or activities
- Boat or watercraft policy , which covers incidents on Texas lakes and waterways
- Rental dwelling policy , which covers landlord liability exposures at properties you rent out
For a closer look at what your home policy covers before the umbrella layer applies, see our overview of homeowners insurance options.
Who needs a personal umbrella policy in Texas
More people than expect to need one actually do. You don't have to be wealthy to be a target for a lawsuit. Anyone with a home, retirement savings, or future earnings is worth suing. Texas does offer some strong asset protections under state law, including the homestead exemption and certain retirement account protections, but wages can be garnished for some judgments and non-exempt assets can be seized. An umbrella policy stops the problem before it starts.
Consider a personal umbrella policy if any of these situations apply to you:
- You own a home. Your home equity is a real asset that can be pursued in a judgment.
- You have a swimming pool, trampoline, or dog. These are the liability exposures insurers call "attractive nuisances" and they generate a disproportionate number of injury claims.
- You drive frequently or have teenage drivers. Teen drivers are statistically the highest-risk group on Texas roads, and any accident they cause can expose you as the vehicle owner.
- You coach youth sports or host frequent gatherings. Greater exposure to other people means greater liability risk.
- You are active on social media. Defamation and libel claims have become real umbrella triggers in the last decade.
- You own rental property. Tenants and their guests can sue you as the landlord.
Texas-specific liability risks that make umbrella coverage worth it
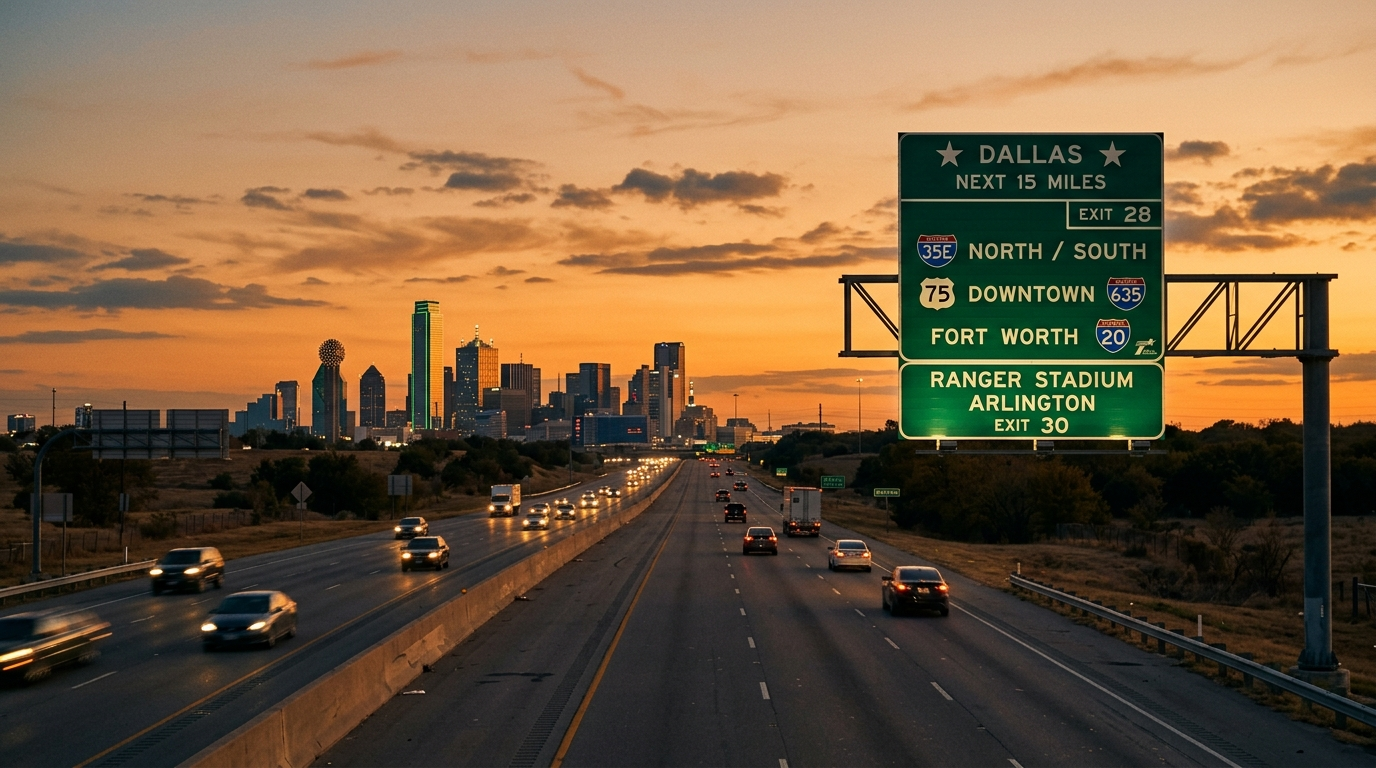
North Texas drivers face some of the most congested highways in the country. The I-635 and I-35E corridor around Dallas sees regular multi-car accidents, and a serious pileup can involve medical costs, lost wages, and pain-and-suffering claims for multiple people. Your standard personal auto policy has per-occurrence limits, meaning the total available for a single accident is capped even if five people are injured.
The DFW housing boom has also brought more backyard pools, outdoor entertaining spaces, and short-term rental activity. Tarrant, Dallas, Collin, and Denton County homeowners hosting Airbnb stays or neighborhood gatherings take on real liability exposure every time someone walks through their door. If you rent your property short-term, note that a personal umbrella usually does not cover commercial short-term rental activity automatically. You'd want to discuss that specific situation with an agent.
Texas is also one of the states where jury awards tend to run high. A 2022 analysis of Texas civil verdicts found multi-million-dollar awards in cases that originally looked modest. Medical costs alone at major Texas trauma centers can run $500,000 or more for a serious injury. Umbrella coverage is priced with that reality in mind.
What a personal umbrella policy covers and what it doesn't
Understanding the scope of coverage prevents unpleasant surprises at claim time. Most personal umbrella policies in Texas cover:
- Bodily injury liability , including medical bills, lost wages, and pain and suffering for people injured by you or your household members
- Property damage liability , covering costs to repair or replace property you damage
- Personal injury claims such as libel, slander, false arrest, and invasion of privacy in many policies
- Legal defense costs , including attorney fees and court costs, which can run into the tens of thousands even when you win
- Worldwide coverage , as incidents that occur outside the U.S. are often included
What umbrella policies generally do not cover includes your own injuries or property damage, intentional acts, business activities conducted from your home, professional liability (that requires a separate policy), and damage covered by your underlying policies that hasn't yet exhausted those limits.
One important Texas note: umbrella policies require you to maintain minimum underlying liability limits. If you reduce your auto policy to bare-bones Texas minimum auto insurance requirements, an umbrella carrier may decline to pay because you didn't maintain the required base coverage. Your agent needs to review all your underlying policies together to make sure the stack works correctly.
How much umbrella coverage do you actually need
A common starting point is to carry at least enough to cover your net worth, but treat that as a floor rather than a target. A $1 million umbrella is the most common entry point and costs very little relative to the protection it provides. Families with significant home equity, investment accounts, or high income should consider $2 million to $5 million.
A simple way to think through it: add up your home equity, any non-retirement investment accounts, vehicles, and savings. Then consider your annual income and how many years of earning power you have left. A judgment can garnish future wages in some Texas circumstances. That total is the minimum, not the ceiling, for your umbrella limit.
Umbrella policies are typically sold in $1 million increments. Going from $1 million to $2 million usually adds only $75 to $100 per year to your premium. That incremental cost is low enough that most families find it hard to justify stopping at $1 million.
How an independent agent helps you buy the right umbrella policy
Not all umbrella policies are the same. The definition of "personal injury," the list of covered watercraft, and the treatment of rental properties all vary by carrier. An independent agent can pull quotes from multiple companies and match the right policy to your actual exposure profile rather than defaulting to whatever one carrier offers.
There is also the coordination question. Your umbrella needs to align with your underlying auto, home, and any other policies so there are no gaps in the stack. If your homeowners liability limit is $100,000 but your umbrella requires a $300,000 underlying limit, you have an uncovered gap of $200,000. Getting this right requires a review of everything together, which is exactly what an independent agent is positioned to do. For more on why that independence matters, see our post on independent insurance agents vs. direct carriers in Texas.
Get a personal umbrella quote from Princeton Insurance
Princeton Insurance is an independent agency serving homeowners, drivers, and families across North Texas, including Dallas, Frisco, Plano, McKinney, Arlington, and the surrounding communities. Because we work with multiple carriers, we can compare options and find the umbrella coverage that fits both your budget and your actual risk exposure.
If you're ready to find out how much a personal umbrella policy would cost on top of your existing coverage, we make it easy. Visit our personal umbrella insurance page to learn more, or contact Princeton Insurance to get a quote. You can also reach us by phone at (469) 916-9595 . A few minutes now could protect everything you've built from a single bad day on the road or in your own backyard.
Get A Quote
At Princeton Insurance, securing your future is easy. Ready to protect what matters? Contact us for a quick quote and personalized insurance options!
Kelly
Speak to Kelly 24/7
Microphone ready
Start your custom insurance quote
Instant answers to your insurance questions
Schedule appointments or follow-ups
Personal Insurance
From auto and homeowners to renters and umbrella policies, we help protect your family and property. Let’s find coverage that fits your life.
Commercial Insurance
We customize policies for your industry's risks, like general liability and workers' comp, ensuring you can run your business worry-free.
Contact Princeton Insurance
Recent Posts